
Term life
“If my income stopped, could they carry on?” Cover for a fixed number of years, sized to replace your income while the people who depend on it still depend on it.
Life cover · Mortgage protection · Final expense
Most people put life insurance off because it feels complicated. It isn’t. We work out what your family would actually need if your income stopped tomorrow, then match you to a policy that covers it.

You insure the car. You insure the house. The people inside them are the part that cannot be replaced.Morgan Williams · Founder
What we help with
Life insurance is not one product. It is a handful of separate jobs, and the right policy depends entirely on which job you need doing.
“If my income stopped, could they carry on?” Cover for a fixed number of years, sized to replace your income while the people who depend on it still depend on it.
“Could they stay in the house?” Cover built around the balance and remaining term of your mortgage, so the roof is not the thing at risk.
“Who pays for the funeral?” Smaller whole-life cover aimed at the immediate costs rather than long-term income, with simplified underwriting.
What it actually costs
Ask most people what life insurance costs and the number they give is well above what a healthy adult in their thirties would actually pay. That gap is the single biggest reason families stay uninsured. Not the price, but an assumption about the price that nobody ever checks.
Your own number depends on your age, your health, how much cover you need and for how long, and it is only ever confirmed after underwriting. The quickest way to stop guessing is to have it worked out properly.
Nobody has ever told me they regretted arranging cover. A lot of people have told me they wished they had done it five years earlier.Morgan Williams · Founder
The honest version
About
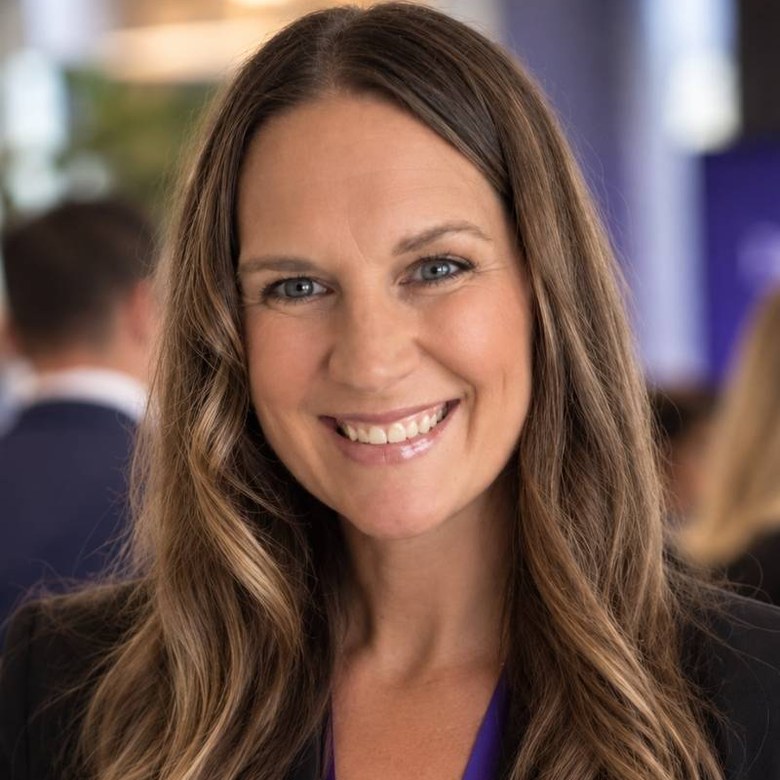
Morgan spent years in a classroom before she ever sold a policy, and it shows in how she explains things. She is also an ICF Professional Certified Coach, which means the conversation tends to start with what you are actually worried about rather than with a product.
No obligation
Tell us a little about who you are protecting and you will get options back by email, with the differences explained. If none of them suit, that is a perfectly good answer.
Takes about two minutes. We do not sell your details.